Which payments belong on the 1099-MISC, which box each one goes in, the thresholds that differ by box, and how to get the records straight before the 2027 deadlines.
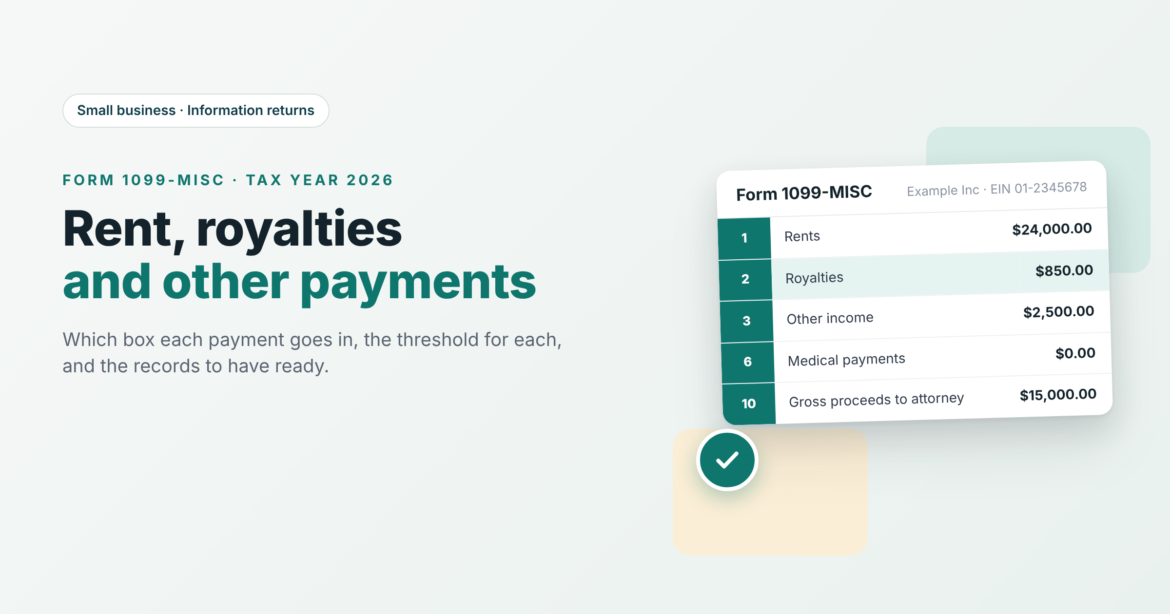
Form 1099-MISC is the catch-all information return: it reports the payments a business makes that are not wages and not contractor compensation, which since 2020 has had its own form, the 1099-NEC. For a small business that means rent paid to a landlord, royalties paid for a license or a mineral interest, prizes and awards, medical payments, and gross proceeds paid to an attorney. Each has its own box, and several have their own thresholds. This guide goes through the boxes a small business is likely to use, what counts, who is exempt, the 2027 deadlines, and the records to have in order before anything is typed.
Which payments go on a 1099-MISC
The quickest way to sort a year’s payments is to ask what the money was for. Services performed by a non-employee go on the 1099-NEC, box 1a. Most other reportable payments a small business makes go on the MISC; interest it pays goes on the 1099-INT. The table below covers the boxes a small business will meet; the rest of the form (fishing boat proceeds, crop insurance, fish purchased for resale, section 409A deferrals) applies to specific industries.
| Box | What it reports | Threshold for tax year 2026 |
| 1 Rents | Office or store rent, equipment rental, land rent, paid to the owner | $2,000 |
| 2 Royalties | Payments for the use of intellectual property, or oil, gas and mineral interests | $10 |
| 3 Other income | Prizes and awards not for services, taxable damages, and other payments that fit no other box | $2,000 |
| 4 Federal tax withheld | Backup withholding taken from any of the above | Any amount |
| 6 Medical and health care payments | Payments to physicians, clinics and other providers in the course of business | $2,000 |
| 7 Direct sales | A checkbox: $5,000 or more of consumer products sold to the recipient for resale | $5,000 |
| 10 Gross proceeds paid to an attorney | Settlement proceeds paid to a lawyer, whether or not the lawyer is the beneficiary | $600 (section 6045(f) was not changed by the 2025 law; confirm in the 2026 instructions) |
| 16 to 18 State | State tax withheld, state number, state income | Per state |
Source: IRS, Instructions for Forms 1099-MISC and 1099-NEC
The $2,000 figure is new for tax year 2026. It replaced the $600 threshold for payments made after December 31, 2025, and will be indexed for inflation in later years. It applies to rent, other income and medical payments. Royalties stayed at $10, which is the box a $2,000 filter silently drops: a business that pays a $900 royalty and screens its vendor list at $2,000 will miss a form it owes.
Rent: the box most small businesses file
Box 1 covers rent the business paid in the course of its trade: the premises, a storage unit, equipment rented for a job, a booth at a show.
Who was paid? Rent paid to a corporation is generally exempt from reporting, so a landlord that is a C or S corporation gets no form. A landlord that is an individual, a partnership or an LLC taxed as either does. Line 3a of the landlord’s W-9 settles it, which is why a W-9 is needed from every landlord, not only the ones you expect to report.
Was it paid to a property manager? Rent paid to a real estate agent or property management company is not reported by the tenant. The manager reports the rent to the owner. If the lease names a management company and the checks go there, the tenant’s obligation ends.
Was it paid by card? Rent paid by credit card or through a payment platform is reported by the card company or platform on Form 1099-K, not by the tenant. Only rent paid by check, ACH, wire or cash goes in box 1.
Royalties: the $10 box
Box 2 reports payments of $10 or more for the use of property that produces royalties: a per-copy fee to use a photograph or a font, a franchise or trademark license, a book or music royalty, an oil, gas or mineral interest. The low threshold means almost any royalty is reportable, and the common error is treating a royalty as a service fee and putting it on the NEC. The test is whether the payee is being paid for the use of something they own rather than for work they did. A designer paid to create a logo is NEC; a designer paid a percentage each time the logo is used is a royalty.
Other income, medical payments and attorney proceeds
Box 3 is the residual box. A business uses it for prizes and awards given to people who are not employees and did not perform services to win them, for taxable damages paid under a settlement, and for payments that are income to the recipient but fit nowhere else. A customer’s prize from a drawing belongs in box 3, while a contractor’s early-completion bonus is compensation and goes on the NEC.
Box 6 reports medical and health care payments the business makes to a provider, for example an occupational health clinic the business pays directly. Unlike most payments, these are reportable even when the provider is a corporation.
Box 10 reports gross proceeds paid to an attorney, typically a settlement paid to a law firm’s trust account. It is reportable whether or not the attorney is the beneficiary, and whether or not the law firm is a corporation. Fees paid to the attorney for legal services, by contrast, are nonemployee compensation and go on the 1099-NEC. A business that settled a dispute in 2026 may owe both forms to the same firm.
The 2027 deadlines
Form 1099-MISC has several due dates where the NEC has one.
| Copy | Due | Notes |
| Recipient copy | February 1, 2027 | January 31 is a Sunday. For a form with an amount in box 8 or box 10 the recipient date is February 15, 2027 |
| IRS, on paper | March 1, 2027 | Paper filing is allowed only below 10 information returns in total |
| IRS, electronic | March 31, 2027 | Through IRIS, the only IRS e-file channel from January 1, 2027 |
Ten or more information returns of any type in the year, counted together, means the business must e-file. A business with four 1099-MISC forms and seven 1099-NEC forms is over the line. From January 1, 2027, the IRS accepts e-filed information returns only through IRIS; the older FIRE system closes to filings on November 19, 2026.
Preparing the records: a short routine
- Export the year’s payments by payee and payment date. Everyone paid by check, ACH, wire or cash; card and platform payments come out first, because the platform reports them.
- Sort each payee by what the money was for. Services to the NEC; rent, royalties, other income, medical and attorney proceeds to the MISC boxes above. One payee can need both forms.
- Apply the right threshold per box. $2,000 for rent, other income and medical payments; $10 for royalties; $600 for gross proceeds paid to an attorney. Do not apply one threshold to the whole list.
- Collect or check the W-9 for every reportable payee. The legal name belongs on line 1, the TIN has to fit the box checked on line 3a, and the form has to be signed. Mark corporations exempt where the box allows it; medical payments and attorney proceeds are reported regardless.
- Check the name and TIN combinations. The IRS TIN Matching program lets a payer test them before filing. Fix mismatches now; after filing they come back as CP2100 notices and backup withholding.
- Tie the totals to the ledger. The sum of each box across all forms should equal the ledger account it came from, with every difference explained.
- File, and keep the acknowledgement. Businesses that use TaxFormHero’s 1099-MISC filing service or a similar IRIS provider get the IRS acceptance back per form; the acceptance, the W-9s and the reconciliation are the file to keep for at least three years from the due date, four if backup withholding was taken.
Frequently asked questions
Do I send a 1099-MISC to my landlord?
If you paid $2,000 or more of rent in 2026 by check, ACH, wire or cash to a landlord who is not a corporation, yes, in box 1. If you paid a property management company, no; the manager reports to the owner. If you paid by card or through a platform, no; the platform reports it on a 1099-K.
What is the 1099-MISC threshold for 2026?
$2,000 for rent, other income and medical and health care payments, for payments made after December 31, 2025. Royalties are reportable at $10. Backup withholding is reported whatever the amount.
When is the 1099-MISC due for tax year 2026?
To recipients by February 1, 2027 (February 15 if box 8 or box 10 has an amount); to the IRS by March 1, 2027 on paper or March 31, 2027 electronically.
Is a 1099-MISC needed for a corporation?
Generally no, with exceptions: medical and health care payments and gross proceeds paid to an attorney are reported even when the payee is a corporation (attorneys’ fees, which go on the NEC, are also reported regardless of entity).
What is the difference between the 1099-MISC and the 1099-NEC?
The NEC reports compensation for services performed by someone who is not an employee. The MISC reports everything else that is reportable: rent, royalties, prizes, medical payments, attorney proceeds. A payee can receive both in the same year.
Enjoy Worthview?
Add Worthview as a Preferred Source on Google to see more of our stories in Search.
Worthview Editorial Team is the shared byline for content created collaboratively by Worthview’s editors and contributors. Since 2008, we’ve published thousands of articles across technology, AI, finance, health, home, travel, and lifestyle. Our editorial process emphasizes original research, reputable sources, regular content updates, and clear attribution. Articles covering higher-trust topics, including health and finance, may also undergo review by qualified subject-matter experts.